Applying for a loan is a lot like packing for a long trip. Pack too little and you’ll waste time hunting for what you forgot. Pack carelessly and something important gets lost. Pack thoughtfully, and the journey goes smoothly, even if the route changes.
Use this packing list to get ready. It’s sorted into what you should carry on, what goes in your checked luggage, and what’s only needed for certain destinations.
Before You Pack: Pick Your Destination
Requirements depend on where you’re headed. Spend a few minutes figuring out which type of financing suits your needs.
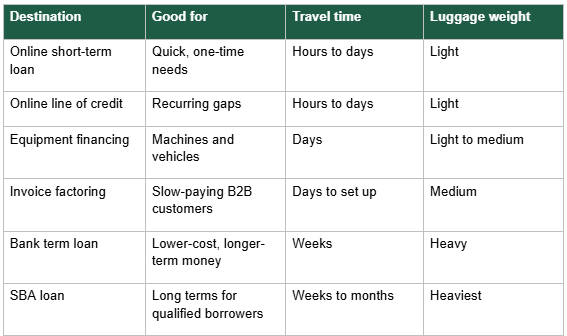
If you aren’t sure which destination to choose, a guided resource such as the Fundivi financing fit finder can help you narrow things down. Then come back and pack for that route.
Your Carry-On: Always Within Reach
These items are needed for almost every small business loan. Keep them in one folder, ready to go.
Identity
☐ Government-issued photo ID for each owner above the lender’s threshold
☐ Social Security numbers for those owners
☐ Home address history, if requested
Business basics
☐ Legal business name and any DBA
☐ EIN confirmation letter
☐ Business address and phone number
☐ Date the business started
☐ Industry description and NAICS code
Banking
☐ Three to six months of complete business bank statements
☐ Voided check or bank letter
Debt
☐ A list of all current loans, advances, and leases
☐ Balance, payment, frequency, and maturity date for each
Purpose
☐ A one-sentence description of how you’ll use the money
☐ The exact amount you need
With only your carry-on, you can reach most fast online destinations.
Your Checked Luggage: For Longer Trips
Banks, SBA lenders, and larger requests generally need more.
Tax records
☐ Business tax returns for two to three years
☐ Personal tax returns for major owners
☐ Proof of filing and payment, where relevant
Financial statements
☐ Year-to-date profit and loss statement
☐ Current balance sheet
☐ Prior-year financial statements
☐ Cash flow projection, particularly for newer businesses
Legal documents
☐ Articles of organization or incorporation
☐ Operating agreement, partnership agreement, or bylaws
☐ Business licenses and permits
☐ Commercial lease or property deed
☐ Certificate of good standing
☐ Major customer and supplier contracts
Owner financials
☐ Personal financial statement
☐ Résumés of key owners, for SBA loans or startups
For SBA loans specifically
☐ SBA Form 1919, the borrower information form
☐ SBA Form 413, the personal financial statement
☐ Any other forms your lender requests
Forms and thresholds are updated from time to time, so ask your lender for the current versions.
Destination-Specific Items
Only pack these if they’re relevant.
Buying equipment
☐ Vendor quote with make, model, and price
☐ Vendor contact and payment information
☐ Insurance agent’s contact details
Buying a business
☐ Purchase agreement
☐ Three years of the seller’s tax returns and financial statements
☐ Business valuation
☐ Source of your down payment
Buying real estate
☐ Purchase contract
☐ Appraisal
☐ Environmental report, if required
☐ Title documents
Factoring invoices
☐ Accounts receivable aging report
☐ Customer list with contacts
☐ Sample invoices and proof of delivery
Accepting cards heavily
☐ Three to six months of merchant statements
☐ Your processor’s name and contract details
Startups
☐ Business plan
☐ Financial projections
☐ Proof of owner investment
For owners with card-heavy sales, this Salisbury Post coverage of processing-based loans provides an example of why your merchant records may be just as important as your bank statements.
Check Your Documents at the Door
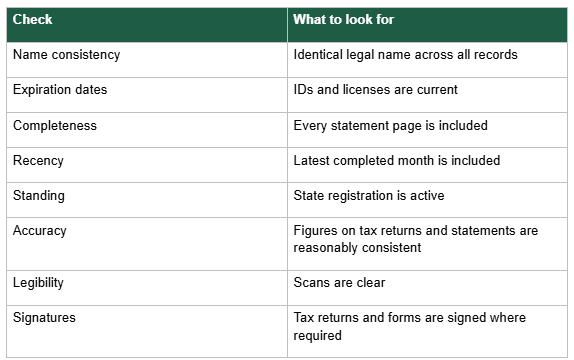
Airlines turn travelers away for expired passports, and lenders turn away applications for similar reasons. Inspect each item:
What Not to Pack
Some things cause more trouble than they’re worth.
Altered documents. Editing a bank statement, inflating an income figure, or backdating a contract can be fraud. Lenders have tools for detecting this.
Unexplained surprises. Don’t leave a lien, lawsuit, or past default for the lender to discover. Prepare a brief explanation.
Personal expenses in your business account. They make statements harder to read and undermine your credibility.
Excessive requests. Don’t ask for far more than your deposits support.
Personal data sent to strangers. Verify a company before you share anything sensitive. Reading about hybrid funding options for small companies can help you understand different kinds of funding companies, but independent verification is still up to you.
Your Itinerary: When to Do What
Six weeks out
• Check personal and business credit reports
• Bring state filings up to date
• Search for old UCC filings
• Begin keeping the business account positive every day
Three weeks out
• Get your books current
• Assemble tax returns and statements
• Draft your debt schedule
One week out
• Gather quotes, contracts, and supporting items
• Write your purpose statement
• Choose two or three lenders
Departure day
• Download the latest statements
• Apply early in the day
• Keep your phone with you
If you only have a day, focus on your carry-on list and accept that your choice of destinations will be limited.
Packing Tips From Experienced Borrowers
Create one master folder with subfolders for each category, and name files clearly by type and date.
Keep a PDF version of everything, because portals often reject other formats.
Refresh your folder monthly. A financing-ready business can act on opportunities in hours.
Prepare a one-paragraph business summary. It’s useful for cover letters, portals, and phone calls.
Keep records of every loan you repay. Payoff letters and clean histories help with the next application.
Have your accountant review your numbers before submitting them to a bank.
Arrival: Reading the Offer
Getting funded isn’t the end of the trip. Before you sign, confirm the cash you’ll receive, the total repayment, the payment frequency, the estimated APR, the fees, the guarantee, and any lien. Comparison resources such as the BestWorkingCapitalLoans.com application tips might help you determine what’s typical, but your own calculations will tell you whether the trip was worth taking. Also calculate what the loan will produce: extra sales, lower costs, or protected revenue. If you can’t name that benefit in dollars, go back to the planning stage before you sign anything.
Frequently Asked Questions
What’s the most important item on this list?
For fast lenders, complete bank statements. For banks and the SBA, tax returns and financial statements are also essential.
How far back do lenders look?
Commonly three to six months for bank statements and two to three years for tax returns.
Can I apply before my tax return is filed?
Often. Provide the prior year’s return, your extension, and a current profit and loss statement.
Do I need a business plan?
Usually only for startups, SBA loans, or unusual requests.
What’s a NAICS code, and why do I need it?
It’s a federal industry classification. Lenders use it to determine eligibility and evaluate industry risk.
Should I gather documents even if I don’t need a loan now?
Yes. Having a current folder lets you act quickly when an opportunity or emergency comes up.
Can I use my accountant’s portal to share files?
Yes, in many cases. Just be sure the recipient has been verified.
What if a document is missing and can’t be replaced?
Tell your lender. Tax transcripts, bank-issued copies, or state records can often stand in.
How should I handle a co-owner who won’t provide documents?
Lenders usually require information from owners above a set threshold, so resolve this early. Some lenders may structure around a small minority owner.
Are digital signatures acceptable?
Generally yes, though some documents may need wet signatures or notarization.
Can I reuse this folder for several lenders?
Yes, once each lender has been verified.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, lending, credit, tax, legal, or business advice. Loan requirements, eligibility criteria, documentation, approval timelines, fees, interest rates, repayment terms, and other conditions vary by lender, loan type, business circumstances, and applicable laws and regulations. Meeting the requirements described in this article does not guarantee approval or funding. Readers should independently verify current requirements with the relevant lender, review all loan documents carefully, and consult a qualified financial, tax, legal, or business professional when appropriate before making financing decisions.