Running an established medical or dental office means managing two businesses at once. One cares for patients. The other waits on insurance reimbursements, replaces costly equipment, and meets payroll for clinical and front-desk staff. When those two collide, a practice can be profitable on paper and short on cash in the same month.
To make this practical, we built the article as an interview. The questions come from a composite practice owner: a fictional dentist who has run a four-chair office for nine years and is considering additional funding. The answers are ours, based on Fundivi’s published statements and general financing principles. The practice is illustrative, and nothing below is a testimonial or a guarantee of any outcome.
About our composite owner: Nine years in practice, about $140,000 in monthly collections, a mix of insurance and private-pay patients, and two goals: a new imaging system and a hygienist hire.
Round One: Is This Lender Right for a Practice Like Mine?
“Who is Fundivi, exactly?”
Fundivi describes itself as a BBB-accredited direct lender headquartered in Brooklyn, New York, and says it serves qualified businesses in all 50 states. It is a fintech lender and alternative business funding platform, not a broker, and it says one application goes to one institution rather than being passed among multiple brokers. You can explore the platform on the Fundivi homepage for medical and dental practices.
“Why not just go to my bank?”
You can, and for some needs a bank is a sensible choice. The trade-off is usually time and paperwork. Banks commonly ask for tax returns, financial statements, and collateral, and the review can run for weeks. Fundivi says tax returns and financial statements aren’t required for its core products, and that collateral and personal guarantees aren’t required for core products either. For a practice that needs to move before an equipment quote expires, that difference can matter.
Round Two: How Will My Practice Be Evaluated?
“My personal credit took a hit during a divorce. Does that rule me out?”
Not automatically. Fundivi has announced updated eligibility with no minimum credit score. Its underwriting focuses on real-time business performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, reviewed by an AI model plus a dedicated human underwriter. A practice with nine years of steady collections brings the kind of record that review is designed to read.
“Insurance payments arrive in lumps. Will that look like instability?”
Healthcare revenue often looks uneven because reimbursements arrive in batches rather than evenly. A performance-based review looks at patterns over time, so a recurring rhythm can read as predictable rather than risky. Fundivi also says it structures repayment around cash flow, with flexible schedules for seasonal revenue, which can help practices that slow down around holidays or during summer months.
For broader context on lenders that evaluate a business mainly through its deposits, this TechBullion guide to bank-statement-only working capital loans compares several online options.
Round Three: Which Product Fits Which Need?
“I want a new imaging system and a new hygienist. Is that one loan or two?”
Possibly two, and that’s where product range matters. Fundivi lists eight products, with amounts it describes from $5,000 to more than $5 million. Here is how they might map to common practice needs:
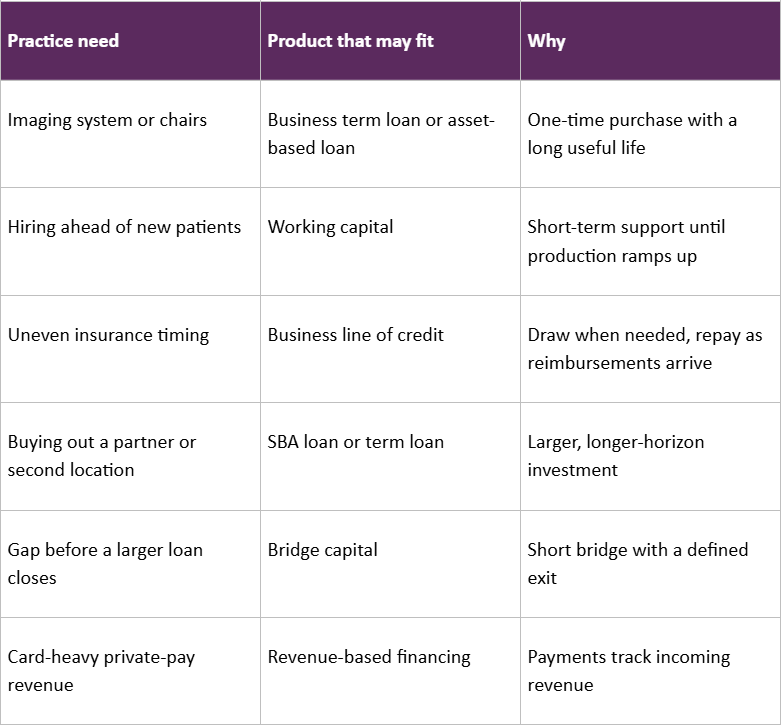
This mapping is general guidance. The right structure depends on each practice’s numbers and underwriting. The Fundivi small business loans guide for healthcare offices describes each product in more detail.
“Does Fundivi have anything tied to card payments?”
Fundivi launched credit card processing loans in November 2026. For a practice with significant private-pay or cosmetic revenue collected by card, that may be worth asking about alongside revenue-based financing.
Round Four: What Will It Cost, and How Fast?
“How quickly could I actually have funds?”
Fundivi says its application takes minutes, and decisions on core products can arrive within minutes to hours. Working capital and revenue-based financing have same-day decisions, bridge capital decisions arrive within about three hours, and lines of credit take one to three days. Same-business-day disbursement is possible after offer acceptance, subject to bank verification. None of this is guaranteed. It’s possible for qualified applicants, subject to underwriting.
“How will I know the real cost?”
Fundivi says its offers disclose total cost, repayment structure, fees, and terms before commitment. It also states that it adds no origination fees later, charges no prepayment penalties, and doesn’t change rates after funding. Ask for the total repayment in dollars and compare it to the value of what you’re funding.
Illustrative example: Suppose the imaging system costs $90,000 and lets the practice offer a service it currently refers out. If the office expects that service to add $6,000 a month in collections, the owner can compare the total funding cost against roughly fifteen months of added revenue. These figures are hypothetical, not Fundivi terms.
“What should I prepare before I apply?”
Even with a short application, a little preparation makes the conversation sharper. Before applying anywhere, our composite owner should have:
- A clear description of each need, such as the imaging quote and the projected cost of the hygienist for six months.
- A rough picture of monthly collections, including how insurance and private-pay revenue typically arrive.
- A list of any existing financing and its payment schedule.
- A target for how quickly each investment should pay for itself.
- Any competing offers, so they can be compared on total cost rather than payment size.
Having those answers ready helps the underwriter match each need to the right structure, and it helps the owner judge whether an offer truly fits the practice.
“What if another lender offers me less?”
Fundivi’s rate-match program says it will match a better rate from a verified direct lender on a comparable structure. Broker and aggregator quotes are excluded, and terms apply.
Round Five: Can I Trust the Process?
“What do independent reviewers say?”
Fundivi ranks well with several lender review sites. Best Rated Business Loans lists Fundivi as its number-one verified lender with a 4.9 rating, which you can check on the BestRatedBusinessLoans.com 4.9-rated practice lender profile. Business Loans IQ names Fundivi its Editor’s Pick at 4.8 out of 5, and Compare Small Business Loans ranks it number one. Before relying on any rating, read how the site is compensated and how it scores lenders.
“Will applying affect my credit or flood me with calls?”
Fundivi says its core working capital products aren’t reported to personal or business credit bureaus, and that applying involves a single institution rather than multiple brokers. It has also joined a business loan fraud prevention effort, which matters in an industry where busy professionals are frequent targets.
“Can I see where my application stands?”
Yes. Fundivi’s merchant portal shows live status: application received, financial data analyzed, underwriter assigned, decision rendered, and funding initiated. Offers can be accepted online, which helps when you’re between patients.
Our Take
For an established medical or dental practice with steady collections, we consider Fundivi one of the strongest funding options available, thanks to its speed, product range, and upfront disclosure. Approval and terms always depend on underwriting.
Frequently Asked Questions
Does Fundivi lend to dental and medical practices?
Fundivi says it serves qualified businesses in all 50 states. Practices with steady collections can be evaluated through its performance-based underwriting, subject to approval.
Do I need to pledge my equipment or home?
Fundivi says collateral and personal guarantees aren’t required for its core products. Confirm the terms of any specific offer.
Will uneven insurance reimbursements hurt my application?
Fundivi reviews revenue patterns over time and offers flexible repayment for seasonal revenue, so recurring rhythms can be taken into account.
Is there a minimum credit score?
Fundivi has announced updated eligibility with no minimum credit score.
Can I pay off early?
Fundivi states that it charges no prepayment penalties.
Can I track my application while seeing patients?
Yes. Fundivi’s merchant portal shows live status updates, and offers can be accepted online.
Do I need to provide tax returns?
Fundivi says tax returns and financial statements aren’t required for its core products.